Foreign buyers purchased $4.4 billion of South Florida homes in 2025, up from $3.1 billion in 2024, and the UK was 2 percent of Broward's foreign buyers, per Miami Realtors. In this LuxuryDade guide, Gerardo Gonzalez covers what changed for British owners on 6 April 2025, when UK inheritance tax moved to a residence test, the US-UK estate tax treaty, GBP planning, financing, FIRPTA and where British buyers buy in 2026.

I work with British buyers across Surfside, Coral Gables, Coconut Grove, and Miami Beach. Three types of UK buyers are active right now: those who are leaving the UK because the non-dom abolition eliminated their tax advantage, portfolio investors diversifying out of London property at GBP/USD 1.35 rates, and lifestyle buyers who want year-round sun and Florida's zero state income tax. All three groups share one characteristic: the ones who close fast and on the best terms have sorted their cross-border tax picture before they toured a single unit. The US-UK estate tax treaty is one of the most buyer-friendly in the world, but it only works if you structure correctly from the start. Before your first developer tour, read my complete guide for foreign national buyers in Miami. Then come back here for the British-specific analysis: treaty protection, GBP currency strategy, UK mortgage options, HMRC reporting requirements, and the neighborhoods where British buyers are clustering in 2026. I will give you specific numbers, not generalizations.
US-UK Estate Tax Treaty: What British Buyers Need to Know
The United States and United Kingdom maintain both an income tax treaty and a separate Estate and Gift Tax Treaty. For British buyers of Miami real estate, the estate tax treaty is the most consequential document. Here is what it means in practice:
My advice for British buyers is to treat FIRPTA and the financing setup as step one. The pound-to-dollar timing and your holding entity decide the return more than the address.
- Estate tax protection: Without a treaty, a nonresident's estate gets a $13,000 credit that shelters only about the first $60,000 of US assets, and rates reach 40 percent. The US-UK estate and gift tax treaty changes that: the IRS instructions for Form 706-NA explain that for a UK national who is neither domiciled in nor a citizen of the US, the treaty places a limit on the US estate tax owed on US property. Advisers usually model that limit as a share of the $15 million 2026 US exemption in proportion to US assets over worldwide assets. Have a US estate attorney run your own numbers.
- UK inheritance tax now follows residence: From 6 April 2025, HMRC charges inheritance tax on foreign assets, a Miami condo included, when you are a long-term UK resident, meaning UK resident for at least 10 of the previous 20 tax years (HMRC manual IHTM47020). Leaving does not end it at once: a long-term resident keeps that status for up to 10 tax years after leaving the UK, per GOV.UK.
- Income tax: US rental income from Miami property is taxed in the US. The US-UK income tax treaty provides a foreign tax credit mechanism so HMRC does not tax you again on the same income. You report the US rental income on your UK Self Assessment and offset it with credit for US taxes paid.
- Capital gains: The US taxes non-resident capital gains on US real property sales. The UK also taxes its residents on worldwide capital gains. The treaty prevents full double taxation through coordination provisions, but both a US CPA and a UK accountant must handle the filings in the year of sale.
- FIRPTA withholding on sale: When you eventually sell your Miami property, the buyer is required to withhold 15 percent of the gross sale price under FIRPTA. A US tax attorney can file IRS Form 8288-B before closing to request a reduced withholding certificate based on your actual anticipated gain rather than 15 percent of the full price.
According to the IRS 2025 Publication 901 (US Tax Treaties), treaty benefits are available only to residents of the UK who are subject to UK tax on the income in question. Work with a dual-jurisdiction tax advisor before you close, not after. The treaty protection is powerful, but it requires timely, correct filings to be effective. See my US tax guide for foreign real estate buyers for a full breakdown of withholding, capital gains, and FIRPTA obligations that apply regardless of treaty status.
GBP to USD Currency Planning for British Buyers
As of April 2026, the GBP/USD exchange rate is approximately 1.35, meaning a $1 million USD Miami condo costs roughly £741,000. The pound traded between 1.32 and 1.38 in 2026, a spread that translates to a roughly £33,000 swing on that same purchase price. For a pre-construction buy with deposits stretched over 30 months, currency risk is significant. Here is how the key exchange scenarios play out at current rates:
| USD Purchase Price | At GBP/USD 1.32 | At GBP/USD 1.35 (Apr 2026) | At GBP/USD 1.38 |
|---|---|---|---|
| $500,000 | £379,000 | £370,000 | £362,000 |
| $1,000,000 | £758,000 | £741,000 | £725,000 |
| $2,000,000 | £1,515,000 | £1,481,000 | £1,449,000 |
| $5,000,000 | £3,788,000 | £3,704,000 | £3,623,000 |
For deposit wires over £100,000, I recommend a currency broker rather than your UK high-street bank. For a full guide to how Miami pre-construction deposit schedules work and what triggers each payment, read my Miami pre-construction buyer guide. Barclays and HSBC typically charge 1.0 to 1.5 percent spreads on GBP/USD conversions. Currency brokers such as Wise Business, OFX, and Moneycorp charge 0.3 to 0.5 percent. On a £750,000 conversion, that spread difference saves £5,000 to £8,000. Forward contracts, available from most currency brokers, let you lock today's rate for conversions up to 12 months out, protecting your sterling cost across multiple deposit milestones during construction.
Best Neighborhoods for British Buyers in Miami
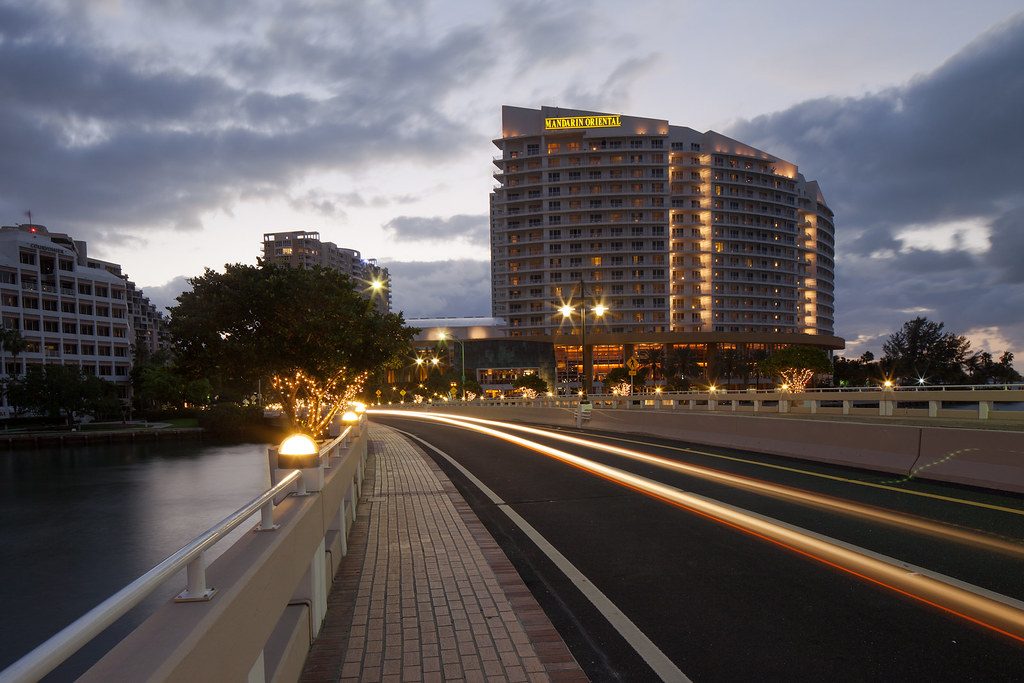
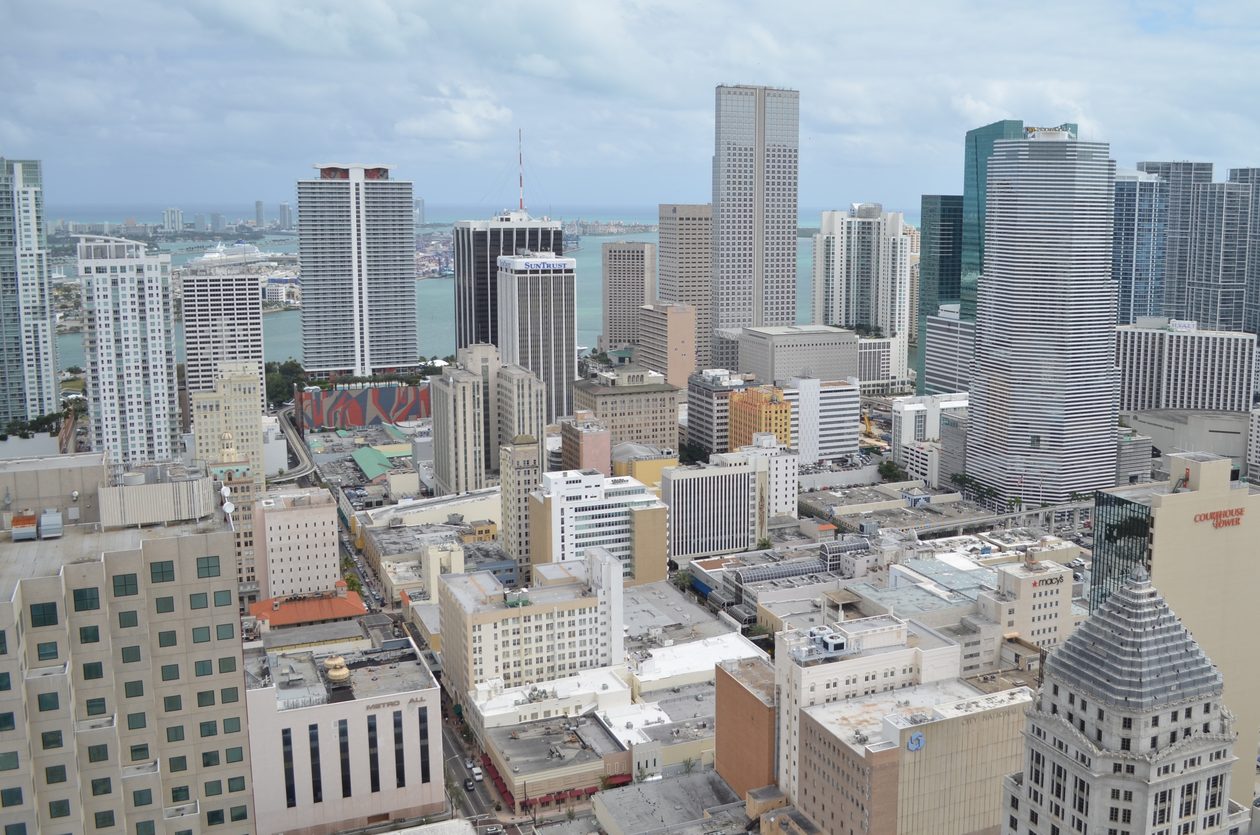
Where British buyers land in Miami depends on what they are optimizing for. Relocators from London want walkability, good schools, and a social scene that feels familiar. Pure investors want rental liquidity and pre-construction upside. Weekend-to-monthly lifestyle buyers want ocean proximity and a quiet, residential feel. Here is where British buyers are concentrating and why:
- Surfside: The fastest-growing British buyer market in Miami. Walkable, residential, and sandwiched between Bal Harbour and Mid-Beach. British families moving with school-age children prefer Surfside for its proximity to K-12 schools and quieter streetscape compared to South Beach. Entry prices run $800,000 to $4 million.
- Coral Gables: British buyers from London suburbs gravitate to Coral Gables for its tree-lined streets, European architecture, and top-ranked public and private schools. The neighborhood skews toward buyers who are relocating rather than investing. Prices range $1 million to $8 million for single-family homes.
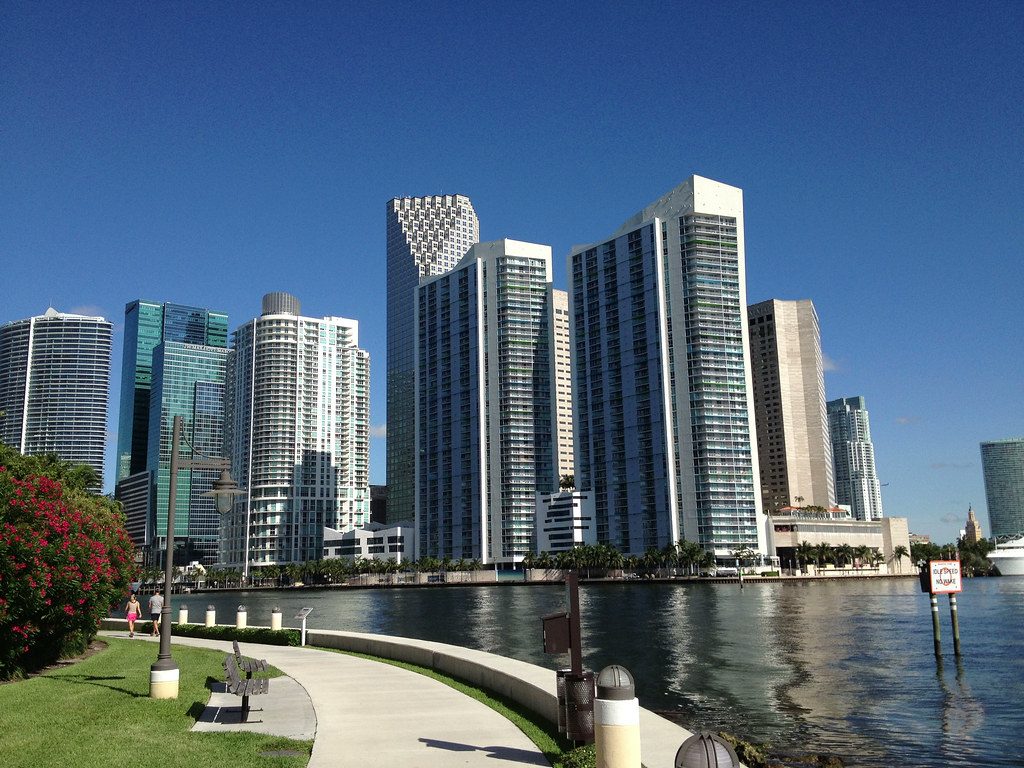
- Coconut Grove: Miami's oldest neighborhood. Walkable waterfront, marinas, and a tight-knit social community that attracts British buyers who want a village feel within a major city. Condo and townhome prices range $500,000 to $5 million. See my Coconut Grove luxury guide for a building-by-building breakdown.
- Miami Beach and Mid-Beach: South Beach attracts British buyers in the entertainment and hospitality industries. Mid-Beach is quieter and more residential. The Faena District and Elysee are popular with British buyers seeking international-brand residences.
- Brickell: British professionals relocating for finance or tech prefer Brickell for its walkability, corporate rental demand, and Brickell City Centre. Strong rental yields from corporate tenants make this the best pure investment neighborhood. See my Brickell luxury condo guide for specifics.
My recommendation: Surfside or Coral Gables for families relocating from London. Brickell for pure investment. Coconut Grove for lifestyle buyers who want a community rather than a hotel-style tower. For a detailed look at what is currently available in each of these areas, see my Miami neighborhood guide with building-by-building analysis across all major markets.
The UK Non-Dom Abolition: Why British Buyers Are Moving to Miami
The UK replaced the remittance basis on 6 April 2025 with a 4-year foreign income and gains (FIG) regime, available only to people who become UK resident after 10 consecutive tax years abroad, per GOV.UK. Everyone else who is UK resident now pays HMRC on worldwide income and gains, Miami rent included, whatever their domicile. For a former non-dom who used to keep US rent outside the UK, that is the change that matters.
For high-net-worth British buyers, this changes the math significantly. A Mayfair resident earning £500,000 in US rental income now faces UK income tax on that income (top rate 45 percent) on top of the US income tax already paid. The US-UK treaty foreign tax credit prevents pure double taxation, but the combined effective rate on US rental income is substantially higher than before the abolition for those who previously sheltered income via non-dom status.
How British buyers are responding:
- Relocating to Florida: Florida has no state income tax and no state capital gains tax. British nationals who establish Florida residency and surrender UK tax residency eliminate HMRC's claim on US rental income entirely. This is the most aggressive restructuring, and it requires genuine relocation, not just a Florida address.
- Holding via US LLC: A US LLC treated as a corporation for US tax purposes can defer profit distribution. This adds complexity but can reduce the timing of HMRC exposure.
- Pure investment without relocation: Buyers who remain UK tax residents accept the combined US-UK tax burden and invest for capital appreciation rather than rental yield, since long-term US property appreciation can exceed the rental yield after-tax disadvantage.
Financing Options for British Buyers in Miami
British buyers do not have the same direct-subsidiary banking advantage that Canadians enjoy, but HSBC Private Bank, Barclays Wealth, and several US foreign national lenders all serve UK buyers actively. Here are the primary mortgage options available to British nationals in 2026:
| Lender | Product | Rate (Apr 2026) | Min Down | Notes |
|---|---|---|---|---|
| HSBC Private Bank (US) | Foreign national mortgage | 6.75-7.5% | 30% | Best for existing HSBC Premier clients |
| Barclays Wealth (US) | Private banking mortgage | 7.0-7.75% | 30-35% | Requires £500K+ relationship |
| US Foreign National Lenders | Full-doc foreign national loan | 7.25-8.0% | 30% | UK pay stubs + bank statements accepted |
| DSCR lenders (US) | Debt-service coverage ratio loan | 7.75-8.5% | 25% | No US income required, based on rent |
| UK equity release / remortgage | GBP loan on UK property | 5.5-7.0% | N/A | Releases GBP equity, funds USD deposit |
The most common strategy I see with British clients: use a UK remortgage or equity release on their London or Home Counties property to free up GBP capital for the Miami deposit, then arrange a US foreign national mortgage closer to closing. According to the Bank of England's April 2026 data, average UK homeowner equity is approximately 58 percent of property value. On a £600,000 London flat, that is £348,000 of accessible equity at current remortgage rates of 5.5 to 6.5 percent. For a full breakdown of DSCR loan options that work for British nationals with no US income history, see my DSCR loan guide for foreign buyers.
LLC vs Personal Name: Ownership Structure for British Buyers
Because the US-UK estate tax treaty provides meaningful protection, British buyers have more flexibility than non-treaty country buyers. But personal ownership is not automatically the right structure. Here is how I evaluate the decision for UK clients:
- Hold personally if: Your total US assets are below $8 million, you plan to use the property yourself most of the year, and you want simple administration. The treaty's pro-rated unified credit can sharply reduce estate tax exposure at this level, and personal ownership avoids LLC formation costs and annual Florida filing fees.
- Hold in a Florida LLC if: Your total US assets exceed $5 million, you plan to rent the property commercially, or you want liability protection from rental guests. An LLC adds a layer of protection from personal liability suits and simplifies transfer to UK heirs without triggering a US probate proceeding.
- UK company or trust as owner if: You are purchasing as a pure investment and want the property on a UK corporate balance sheet or family trust. This brings US corporate income tax (and possibly branch profits tax) on the company, plus UK corporate and ATED considerations, and requires specialist US-UK tax advice. Only appropriate for institutional-scale purchases or family office structures.
- US-UK dual trust structure if: You have significant UK inheritance tax exposure alongside US estate tax concerns. A cross-border trust can address both simultaneously, but the setup costs are substantial (£15,000 to £50,000 in legal fees) and only justified for portfolios above $5 million.
According to the American Bar Association's 2025 international real estate tax guidelines, the treaty credit's protection is powerful but subject to legislative risk. The US unified credit has changed multiple times and could change again with future legislation. I recommend a US-UK dual-jurisdiction attorney review for any British buyer purchasing above $2 million. See my LLC structuring guide for foreign buyers for cost breakdowns and structure comparisons.
Pre-Construction Deposits: Currency Planning for British Buyers
Miami pre-construction requires substantial cash before a mortgage enters the picture. For British buyers, each deposit milestone is a foreign currency conversion event. Understanding the GBP cost at each stage lets you plan forward contracts and UK equity draws well in advance. Here is a typical branded tower deposit schedule and what it means in sterling at April 2026 GBP/USD 1.35 rates (each developer sets its own, so confirm yours in the purchase contract):
| Deposit Stage | USD (on $1.5M unit) | GBP Equivalent | Typical Timeline |
|---|---|---|---|
| Reservation deposit | $75,000-$150,000 (5-10%) | £56,000-£111,000 | Day 1-14 |
| At contract execution | To 20% total ($300,000) | £222,000 | 30-60 days after reservation |
| At groundbreaking | +10% ($150,000) | £111,000 | 6-12 months after reservation |
| At top-off / structural | +5-10% ($75,000-$150,000) | £56,000-£111,000 | 18-24 months in |
| At closing | Balance 60-70% + closing costs | £666,000-£777,000 | 28-36 months out |
On this $1.5 million unit, the pre-closing deposit obligations total $450,000 to $600,000 USD, equivalent to £333,000 to £444,000 at current rates. A 5 percent GBP depreciation against USD would add approximately £22,000 to that total. For UK buyers I lock the forward contracts at reservation, starting with the largest milestone, because sterling can move more over a 30-month build than any fee you will negotiate. Moneycorp and OFX both offer forward contracts for UK buyers with up to 12 months of coverage, no account fee, and 0.5 percent or less spread. Your broker can set up milestone-triggered conversions that execute automatically on each deposit due date. For a detailed breakdown of what happens if a developer defaults before delivery, see my pre-construction default guide.
Step-by-Step Buying Process for British Buyers
Here is the exact sequence I walk British clients through from first inquiry to closing:
- Consult a US-UK dual-jurisdiction tax advisor before viewing properties. Ownership structure, HMRC reporting obligations, and treaty elections must be decided before you sign anything. Structure changes made after contract execution are expensive or impossible.
- Determine your HMRC status. If you are a UK tax resident who will remain in the UK, accept the worldwide income reporting requirement and plan your tax credit coordination. If you are relocating to Florida and surrendering UK tax residency, work with an immigration attorney alongside your tax advisor.
- Open a US bank account. HSBC US, Barclays US, or any major US bank. You need a US account to receive developer escrow wire instructions and pay monthly HOA fees without constant international transfer friction. HSBC Premier clients can open a US account from the UK without travelling.
- Engage a GBP currency broker. OFX, Moneycorp, or Wise Business. Set up forward contracts for your first two deposit milestones at today's GBP/USD rate before it moves against you.
- Get mortgage pre-approval if you plan to use financing. Pre-approval from HSBC Private Bank or a US foreign national lender takes 3 to 6 weeks. Pre-approval strengthens your position in any developer price negotiation.
- Reserve the unit. Sign the reservation agreement and fund the initial deposit within the 10 to 14-day deadline. Have a Florida real estate attorney review the contract before you sign.
- Manage intermediate deposits over 12 to 24 months of construction, each triggered from your forward contract schedule.
- Close. Fund the balance (mortgage + cash), receive keys, file your first year HMRC self-assessment reporting US property ownership and any rental income. Appoint a US property manager if you will not occupy immediately.
A multi-year pre-construction build can span 3 UK tax years, requiring 3 coordinated HMRC filings and multiple GBP conversion events. Plan early and build the full cost in sterling before you commit. Read my foreign national buyer guide for the complete framework that applies across all nationalities, then return here for the UK-specific details covered in this guide.
"British buyers I work with right now are sharp on the tax picture: they know the non-dom rules changed, they understand the GBP/USD rate matters across a 30-month deposit schedule, and they have already spoken to a US-UK attorney before they call me. The ones who move fastest are the ones who sorted the structure before the unit they want went under contract."Gerardo Gonzalez, Licensed Real Estate Agent at Compass
Frequently Asked Questions: British Buyers in Miami
Ready to Work with Gerardo?
Book a 30-minute call. I walk you through specific buildings, units, and numbers relevant to your situation. No pitch, just analysis.
Book a ConsultationPrefer to talk? Call me at (305) 964-8614 or WhatsApp.